








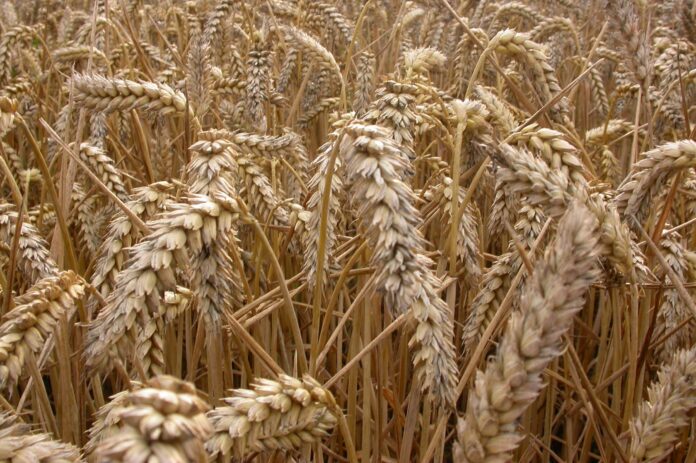
Australia’s 2024-25 wheat harvest exceeded expectations, with yields and quality surpassing initial forecasts. The total production is now estimated at over 32 million metric tonnes, about 2 million tonnes higher than expected, driven by strong yields across most growing states.
Wheat prices rose in January, ending at $257 per metric ton for Australian Premium White (APW) and $242 per metric ton for Australian Standard White (ASW). Despite some volatility in the Australian dollar, the harvest has boosted wheat prices, especially for feed wheat.
The large crop of mid- and low-protein wheat has made Australian wheat highly competitive in Southeast Asia. The region has shown strong demand for Australian feed wheat, with limited competition from other producers. Additionally, Australia’s milling wheat is now more competitive due to favourable freight rates and a weaker Australian dollar, making it an alternative to South America and Canada.
In Western Australia, about 60% of wheat produced was lower-protein grades, including ASW9 and feed wheat, while Eastern states, especially New South Wales, produced higher-protein and hard milling wheat, strengthening Australia’s market position in the Southeast Asian market.
Despite the positive outlook, challenges remain. Some flour millers in North Asia have raised concerns about the lower protein content in Australian noodle wheat this season. Additionally, trade tensions, particularly between the US and China, are creating uncertainty in the market, though Australian wheat exports to Asia are not expected to be directly affected.
As global wheat markets evolve, attention is shifting to the potential impact of US tariffs on Canadian, Mexican, and Chinese imports, which could affect wheat prices and trade dynamics.